Choosing between a SIP (Systematic Investment Plan) and a lumpsum is one of the first decisions every mutual fund investor makes. This post explains both with numbers, a checklist and the formulas.
Note: All figures here are illustrative assumptions, not forecasts. Mutual fund investments are subject to market risks, read all scheme related documents carefully.
The short answer
If you earn a monthly salary, a SIP usually fits naturally. If you have received a large one-time amount (a bonus, maturity proceeds, an inheritance), you have a real choice to make. Neither is "always better"; it depends on your cash flow and how you feel about market swings.
How each one works
SIP: invest a fixed amount every month
A SIP moves a fixed amount from your bank account into a fund on a date you choose. You buy more units when prices are low and fewer when they are high. Over time this averages out your cost, an idea often called market timing rupee-cost averaging.
Things a SIP gives you:
- A habit: investing happens automatically.
- A low entry point: minimum SIP amounts vary by scheme, so check the scheme document.
- Flexibility: you can pause, step up or stop it.
Lumpsum: invest everything at once
A lumpsum puts the whole amount to work from day one. If markets rise afterwards, you benefit on the full amount. If they fall, you feel it on the full amount too.
A note on timing
Nobody can reliably predict the best day to invest. Many investors who are nervous about a large lumpsum split it into equal parts over a few months. This is called a systematic transfer plan (STP).
Side-by-side comparison
| Feature | SIP | Lumpsum |
|---|---|---|
| Typical source | Monthly income | Bonus, sale, maturity |
| Entry point | Small, regular | Large, one time |
| Timing risk | Spread over many months | Concentrated on one day |
| Discipline needed | Low (automated) | Medium |
| Best for | Long-term goal building | Surplus cash on hand |
A worked example
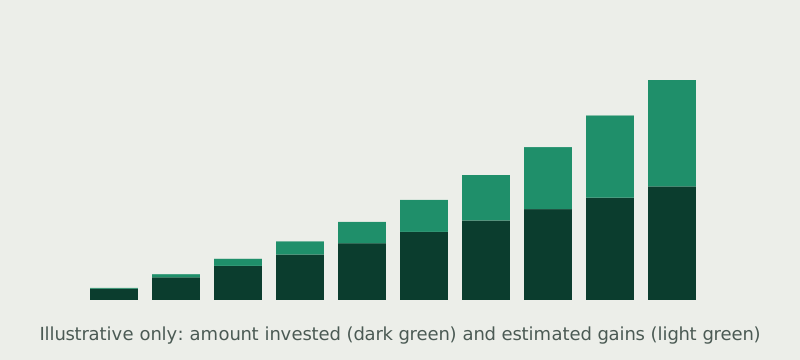
Suppose you invest ₹10,000 a month for 10 years, and the fund earns an assumed 10% a year. The projected value is roughly ₹20.7 lakh on ₹12 lakh invested. These numbers are an illustration of compounding, not a promise.
The formula for a SIP with instalments at the start of each month is:
export function sipFutureValue(monthly: number, annualPct: number, years: number): number {
  const i = annualPct / 100 / 12; // monthly rate
  const n = years * 12; // number of instalments
  return monthly * ((Math.pow(1 + i, n) - 1) / i) * (1 + i);
}
The same calculation in Python:
monthly, rate, years = 10_000, 0.10, 10
i, n = rate / 12, years * 12
fv = monthly * (((1 + i) ** n - 1) / i) * (1 + i)
print(round(fv))  # 2065520
The inputs as JSON, and a command to run the project's tests:
{ "monthly": 10000, "annualReturnPct": 10, "years": 10 }
pnpm test
A fenced block with no language is shown as plain text:
Invested:  12,00,000
Projected: 20,65,520
You can try your own numbers with the SIP calculator, or read more on the AMFI website and the SEBI website.
Which should you choose?
Work through this checklist before deciding:
- I know my goal and how many years away it is
- I have an emergency fund of six months of expenses
- I have checked the fund's costs and risk level
- I have decided how much I can invest without needing it back soon
Then, in order:
- Write down the goal, the amount and the date.
- Decide how much you can invest every month.
- For any one-time amount, choose between investing it at once or in parts.
- If a fall of 20% would keep you awake at night, prefer to invest in parts.
- If you are comfortable with swings and invest for 7+ years, a single investment is reasonable.
- Review once a year.
Common mistakes
- Stopping a SIP when markets fall. Falling markets are when SIPs buy more units.
- Chasing last year's best fund. Use
expense ratio, risk level and fit with your goal instead. - Not stepping up. Raising a SIP by 10% a year can change the outcome a lot; the step-up SIP calculator shows how.
Summary
Use a SIP to build wealth steadily from income. Use a lumpsum for surplus cash, and consider spreading it out if timing worries you.1 Always match the choice to your goal and your comfort with risk.
Footnotes
-
Spreading a lumpsum over several months reduces timing risk but also delays being fully invested, so it can lower returns when markets rise steadily. ↩
Illustration only. Mutual fund investments are subject to market risks, read all scheme related documents carefully. Past performance is not indicative of future returns.
Your next steps
See it with your numbers
Change one number at a time and watch what happens. It is a teaching tool, not a promise.
Open calculatorsTalk it through
Free. 30 minutes. No obligation. No pressure to invest. What you read here goes into the message.
You see the message first, and can change it. Gunasekaran replies Mon–Sat, 10:00–18:00 IST.
Gunasekaran Mookkan
AMFI-registered Mutual Fund Distributor
ARN-311721 · Check on AMFI
Gunasekaran Mookkan is an AMFI-registered mutual fund distributor in Trichy, trading as mugrow. Clients work with Gunasekaran to turn goals like education, marriage and retirement into simple monthly SIPs, with every cost and risk explained in plain words.
More about me →